

On October 19, 2026, J.P. Morgan announced that it had put its deposit token, JPM Coin, on Ethereum.
Photo: Kidfly182, Wikimedia Commons, CC BY 4.0, modified

A deposit token is a token that represents a bank deposit on a blockchain. Ethereum is a blockchain that anyone can join, in other words a public blockchain. In June of the same year, major U.S. banks announced that they would build a shared payment network for sending deposit tokens between banks. The news came as banks move to use deposits on blockchains.
Here is the key point. J.P. Morgan lets screened institutional clients send JPM Coin to each other on Ethereum. JPM Coin is a token that represents U.S. dollar deposits held in J.P. Morgan accounts on a blockchain. That makes it different in structure from stablecoins, whose issuers hold reserve assets separately. A stablecoin is digital money designed to keep its value fixed to a currency such as the U.S. dollar. When J.P. Morgan first moved onto a public blockchain in 2025, it pointed out that the money used to pay for trades there was mainly stablecoins. JPM Coin was offered as an alternative. In this Ethereum announcement, J.P. Morgan gave as its reason that institutional clients' assets and trading counterparties are already on Ethereum.
What moves on the blockchain is a token that represents the deposit, and the dollars do not leave J.P. Morgan's bank. This is not J.P. Morgan's first public blockchain either. It first issued JPM Coin on Base, a blockchain built by Coinbase, in November 2025, and Ethereum is the second.
Why did a bank that ran its own blockchain come out onto public blockchains? And how is its token different from a stablecoin? Let's walk through J.P. Morgan's explanation.
Even When the Token Moves, the Money Doesn't Leave J.P. Morgan's Bank
J.P. Morgan defines JPM Coin as "a deposit token issued by a bank, neither a cryptocurrency nor a stablecoin."
Using it is simple. An institutional client puts dollars into a J.P. Morgan blockchain deposit account, which is separate from a regular deposit account, and converts those dollars into JPM Coin. The coin can be turned back into dollars at any time, and there is no lock-up period.
Both the sender and the receiver of the token are J.P. Morgan institutional clients. According to J.P. Morgan, even when Institution A sends JPM Coin to Institution B, the dollars the token represents do not leave J.P. Morgan's bank. Anyone can join Ethereum, but only counterparties that have been screened and approved can take part in JPM Coin transactions.
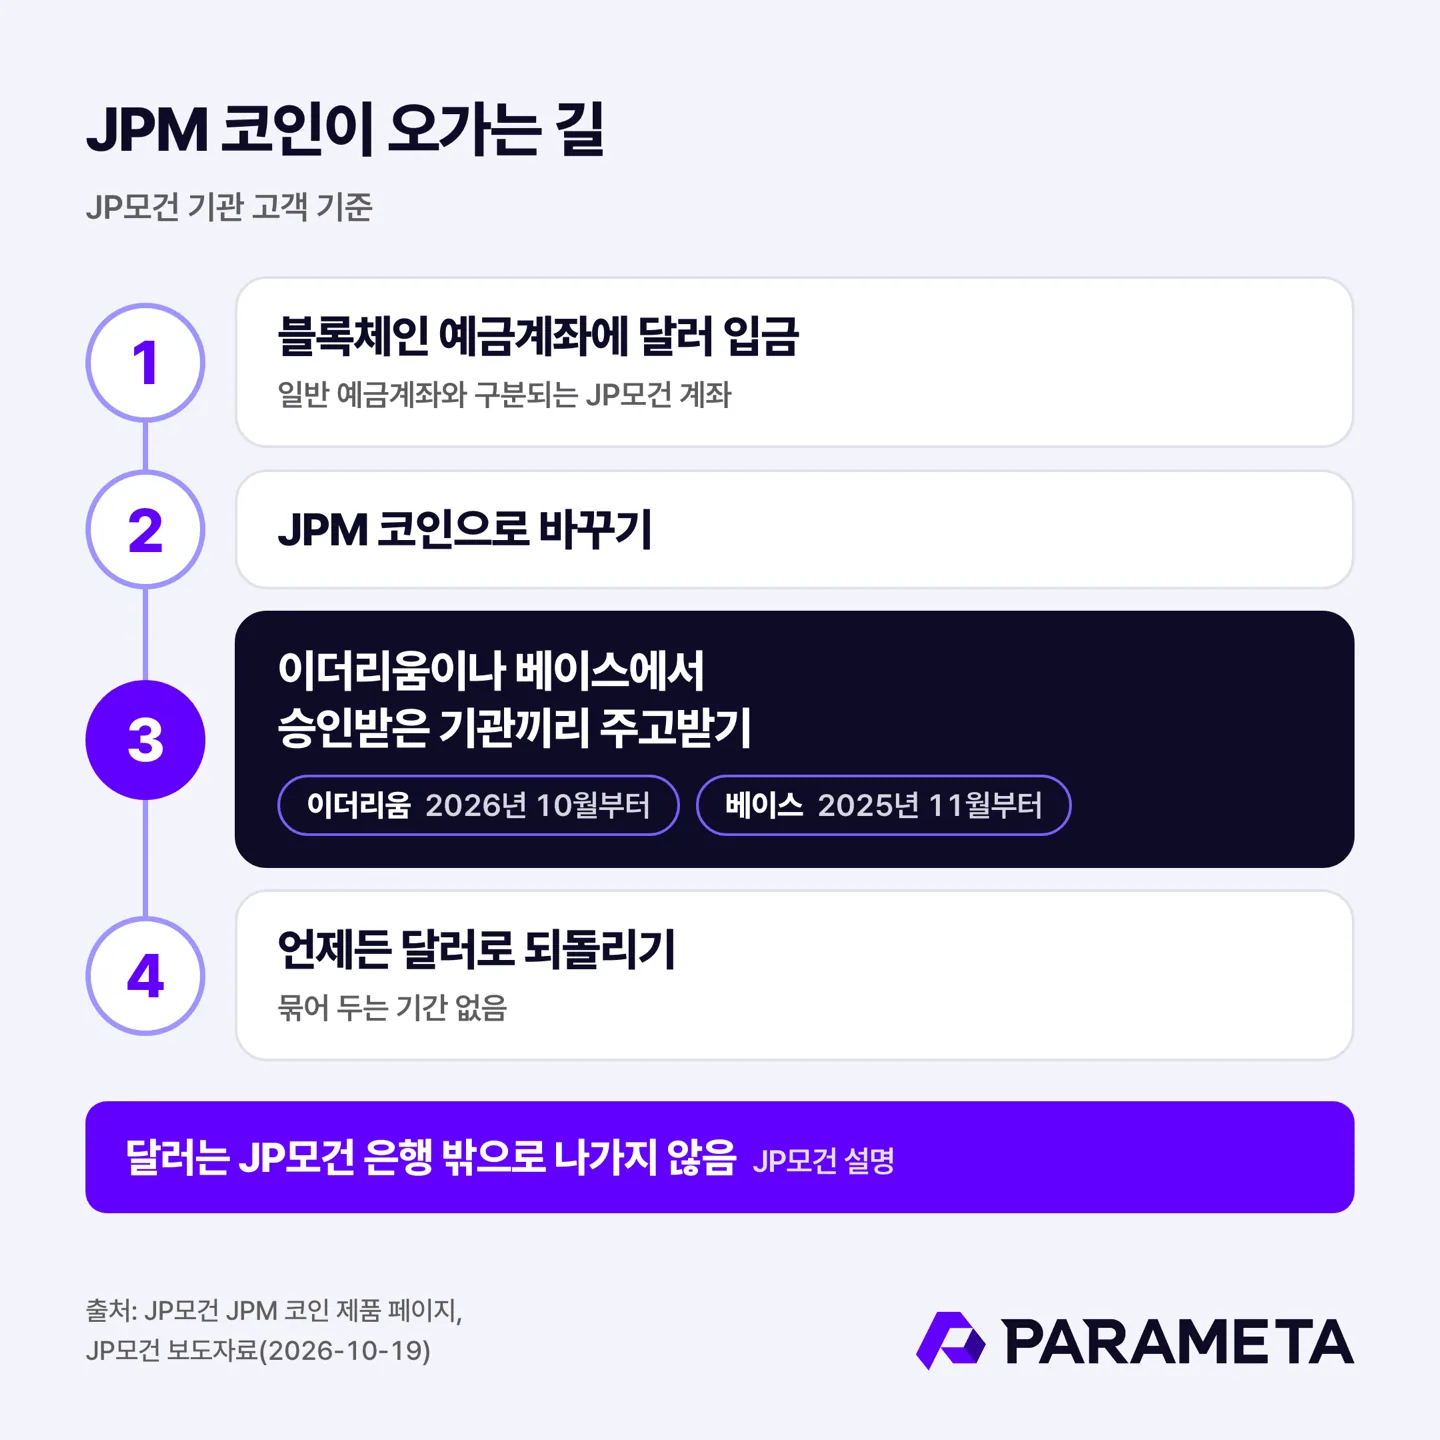
JPM Coin went through a trial issuance (proof of concept) on Base in June 2025 and was officially launched for institutional clients in November 2025. At that time, J.P. Morgan described itself as "the first bank to issue a U.S. dollar deposit token on a public blockchain." Base is a separate blockchain built on top of Ethereum (layer 2), while this time JPM Coin went onto Ethereum itself (layer 1). Institutional clients can now send JPM Coin directly to each other on both Base and Ethereum.
Stablecoins Hold Reserve Assets Separately, While JPM Coin Represents J.P. Morgan Deposits
Both are digital money used like dollars on a blockchain, so they look similar on the surface. The difference lies in who issues them and what the holder relies on. As the basis for comparison, we use the GENIUS Act, the U.S. law on payment stablecoins enacted in July 2025.
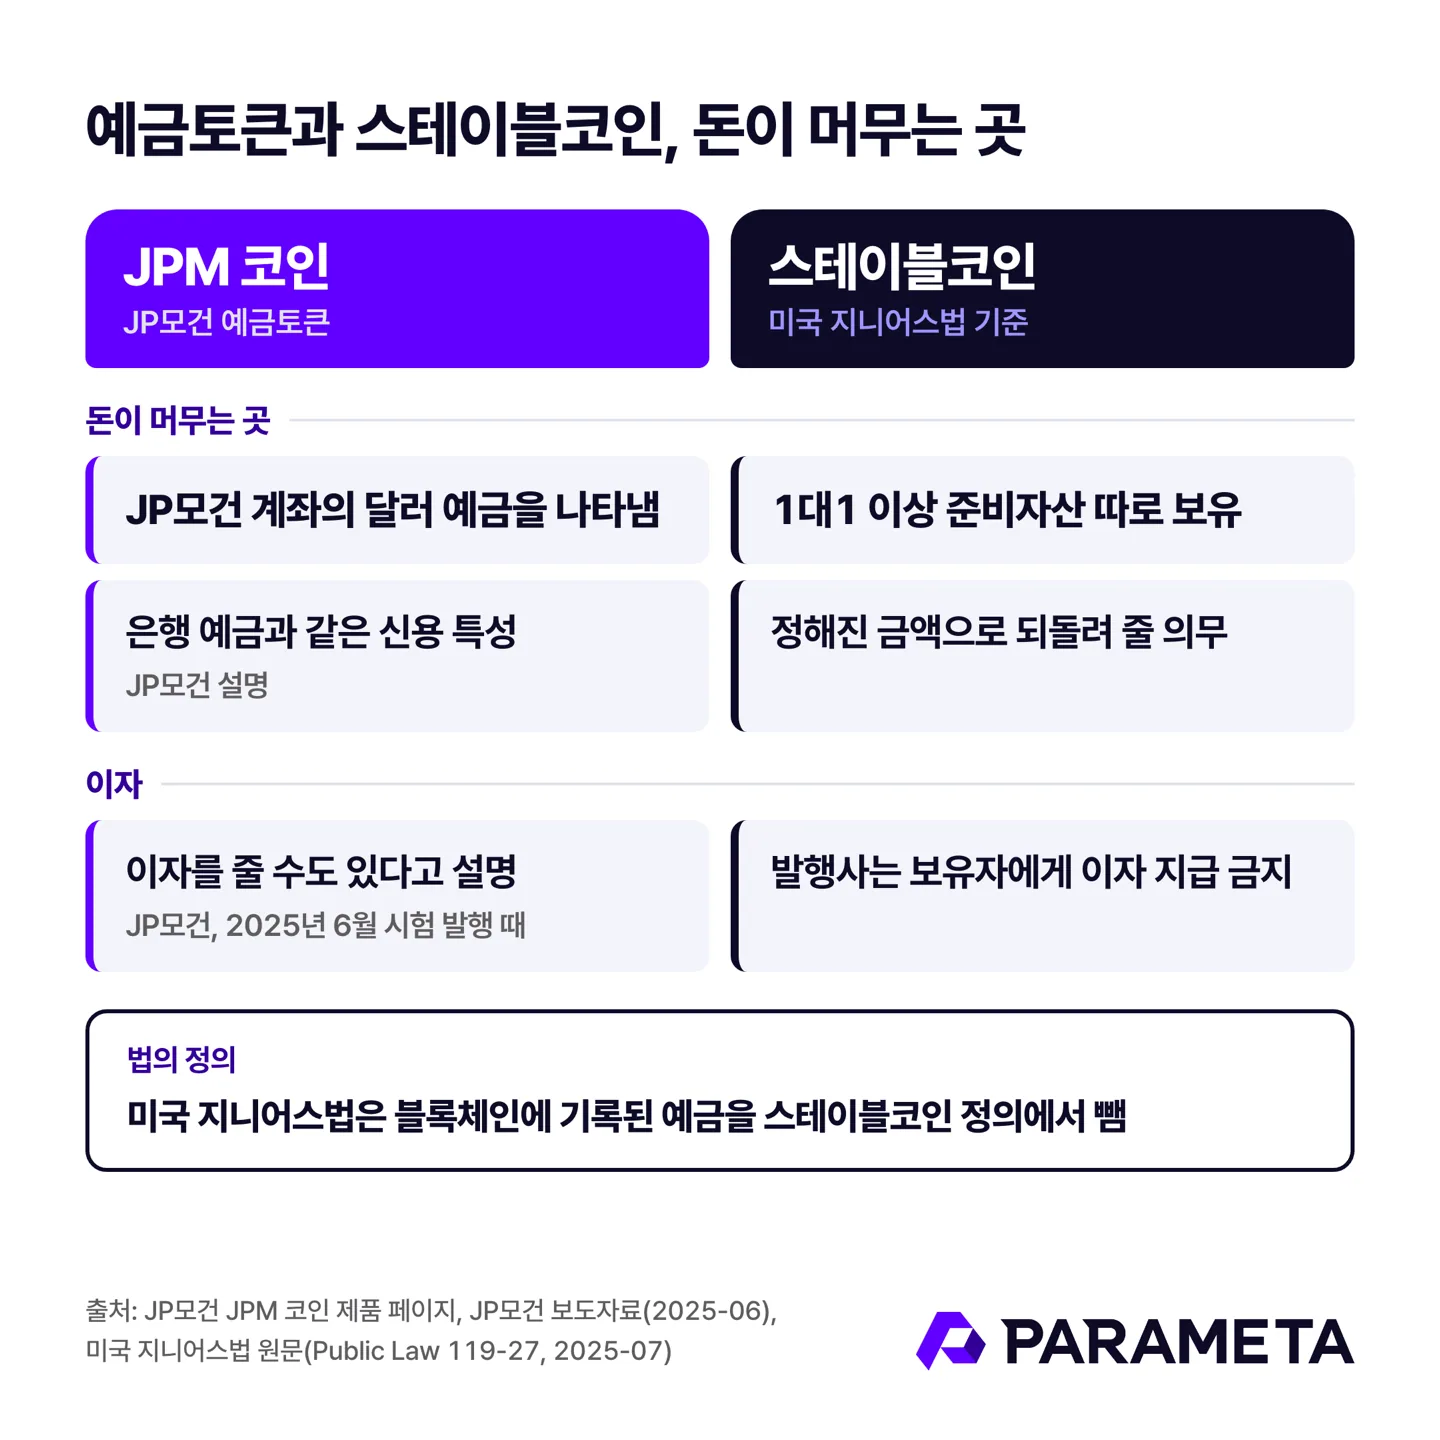
The first difference is where the money is. Under the GENIUS Act, a stablecoin issuer must hold reserve assets separately, at least one-to-one with the tokens it has issued. It must also redeem the tokens for holders at a fixed amount. What holders rely on is this obligation of the issuer and the reserve assets held separately. JPM Coin is different. The token represents U.S. dollar deposits held in J.P. Morgan accounts. J.P. Morgan explains that JPM Coin has the same credit characteristics as a regular bank deposit, meaning it can be trusted as much as a bank deposit. According to J.P. Morgan, what an institution holding JPM Coin relies on is a deposit at a bank, J.P. Morgan.
The second is interest. The GENIUS Act bars stablecoin issuers from paying interest to holders. It blocks interest or yield paid simply for holding or using the token. By contrast, during the trial issuance in June 2025, J.P. Morgan explained that a deposit token could also pay interest to holders.
Third, the law treats the two separately. The GENIUS Act does not regard deposits as stablecoins. It also states separately that deposits recorded on a distributed ledger such as a blockchain (a technology in which many participants share and record the same ledger together) are not stablecoins.
Why J.P. Morgan, Which Had Its Own Blockchain, Came Out to Ethereum
This raises a question. J.P. Morgan's blockchain unit, Kinexys, has been running blockchain financial services since 2015. It has operated client deposit accounts on its own private blockchain. By J.P. Morgan's internal count, the Kinexys platform as a whole has processed more than USD 4 trillion in total, with an average of USD 7 billion a day. The first time Kinexys used a public blockchain was the trial issuance in June 2025.
At the time of the trial issuance, J.P. Morgan wrote that until then the money used for payments on public blockchains had mainly been stablecoins. It also said deposit tokens would be an alternative to stablecoins for institutional clients. It is an alternative that allows near-instant payment 24 hours a day.
In the October 2026 Ethereum announcement, J.P. Morgan pointed to demand. Large institutions that trade both virtual assets and real-world asset tokens (real-world assets such as funds or bonds turned into tokens) are increasingly looking for money to pay for trades on blockchains. J.P. Morgan added that what these institutions want is money issued by a trusted financial institution and connected to the deposit products they already use.
J.P. Morgan also explained why it chose Ethereum: a large amount of funds and tokenized assets are already gathered there. The idea is to keep the money for payments on the blockchain where clients' traded assets, collateral and counterparties already are.
The Question JPM Coin Raises Is "Where, and With Whom?"
Similar experiments are under way in Korea. In Project Hangang, in which the Bank of Korea issued deposit tokens together with banks, the question shifted this year toward testing "can people actually use it?" as the project moved into Phase 2. If that question is "can it be used," JPM Coin points to the next one: which blockchain to put deposit tokens on, and with whom to let them be exchanged.
From the issuer's point of view, two choices in JPM Coin stand out. One is deciding at the issuance stage who can hold the token, and the other is letting money move between bank accounts and the token at any time.
To let only screened institutions receive the token, the issuer has to create and manage a list of institutions that can receive it. PARAMETA's ParaSta supports the issuance and operation of digital assets such as stablecoins and deposit tokens on a single platform, and connects directly to existing banks and payment networks. Its issuance features include control tools such as these allow lists (whitelists) and block lists, multi-signature (execution only after several people approve together), proof of reserves, and freezing of funds. With these tools, it manages everything from issuance to checks after issuance (post-verification).
The First Question to Ask Is Whether a Token Represents Deposits or Relies on Reserve Assets
If you are at a financial company or fintech looking at money on blockchains, there are three questions to take straight from the JPM Coin case.
1. Is the blockchain money we plan to use a token that represents bank deposits, or a stablecoin whose issuer holds reserve assets separately? As we saw above, in the U.S. this distinction changes the legal definition and also decides whether the interest ban on stablecoins applies.
2. Who can hold this token? Whether to accept only screened counterparties or keep it open has to be decided at issuance.
3. Which blockchain are our clients' assets and counterparties on now? The reason J.P. Morgan gave for choosing Ethereum was also an answer to this question.