

In recent public research, a16z crypto described the collateral deposit flow behind stablecoin-linked card programs.
The research also notes that these funds aren't direct stablecoin spending — they're collateral backing card spending.
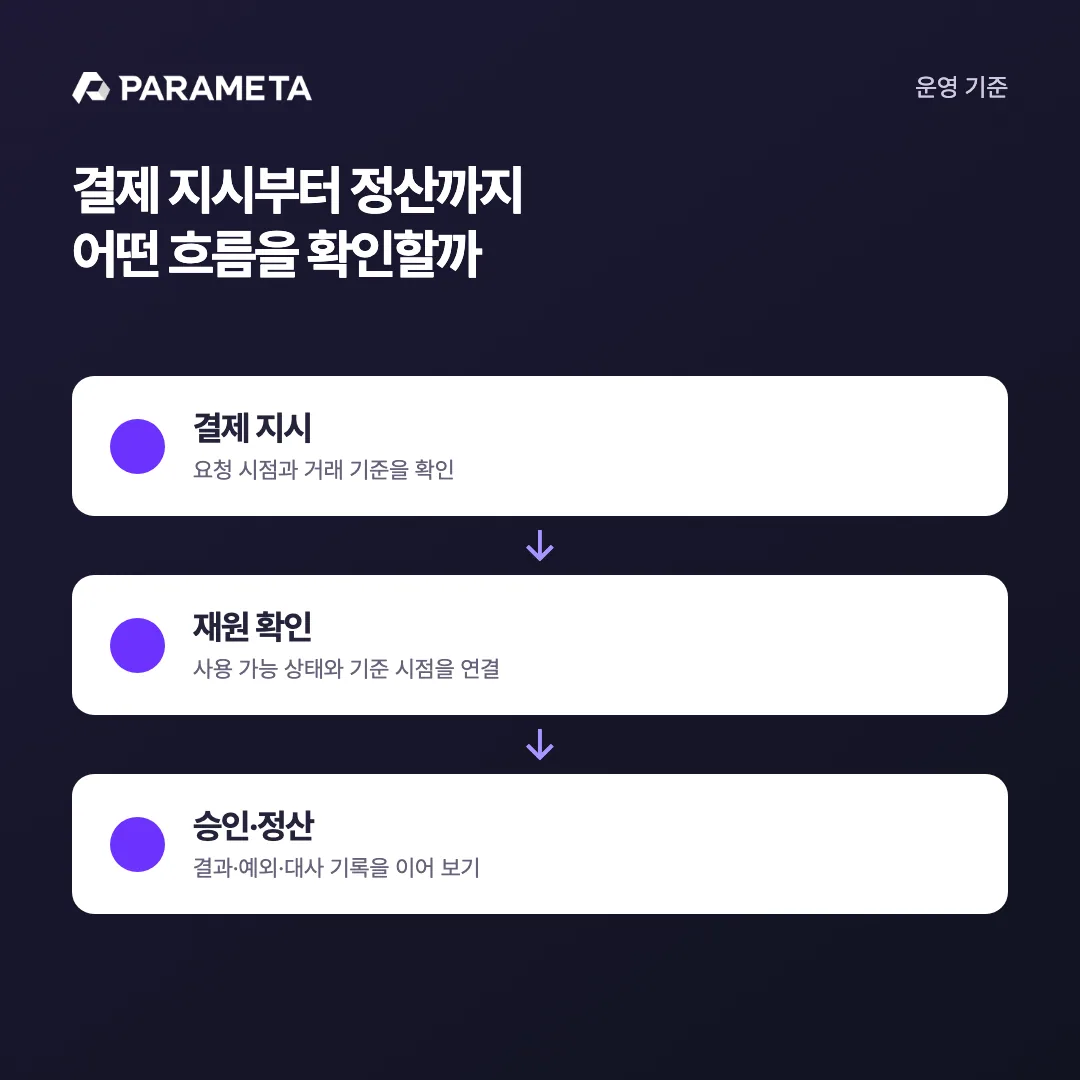
That distinction matters. Even when a payment looks like the familiar experience of a card transaction, behind it, the payment instruction, funding status, authorization outcome, and settlement record all have to connect. Rather than any specific service's availability or performance, this piece looks at what operations teams should define first when this kind of payment flow gets wired together.
The More Card Payments Get Involved, the More the Boundaries of the Payment Flow Matter
To users and merchants, a card payment looks like a simple experience. From an operations standpoint, though, the moment a payment request arrives, the moment available funds are confirmed, the moment an approval or decline is finalized, and the moment it's later reflected in settlement can all be different events.
That's especially true in a structure where collateral, wallet balance, and the state of an external payment network all move together — you need a record of what was decided at which stage. Treating this only as an after-the-fact settlement problem isn't enough; it has to be designed as a set of verification criteria before and after payment, or you won't be able to explain operational discrepancies.
1. Align the Reference Point for Payment Instructions and Funding Status
The fact that a payment request was received and the fact that usable funds were actually confirmed need to be managed as separate things. You need a record of when funding status was checked, whether it was checked again right before approval, and what happens when that check comes back different.
With that reference point clear, a change in balance or collateral doesn't just mean recalculating the result — you can trace back exactly what information the payment decision was based on.
2. Approvals, Declines, and Cancellations Need to Share One Record Structure
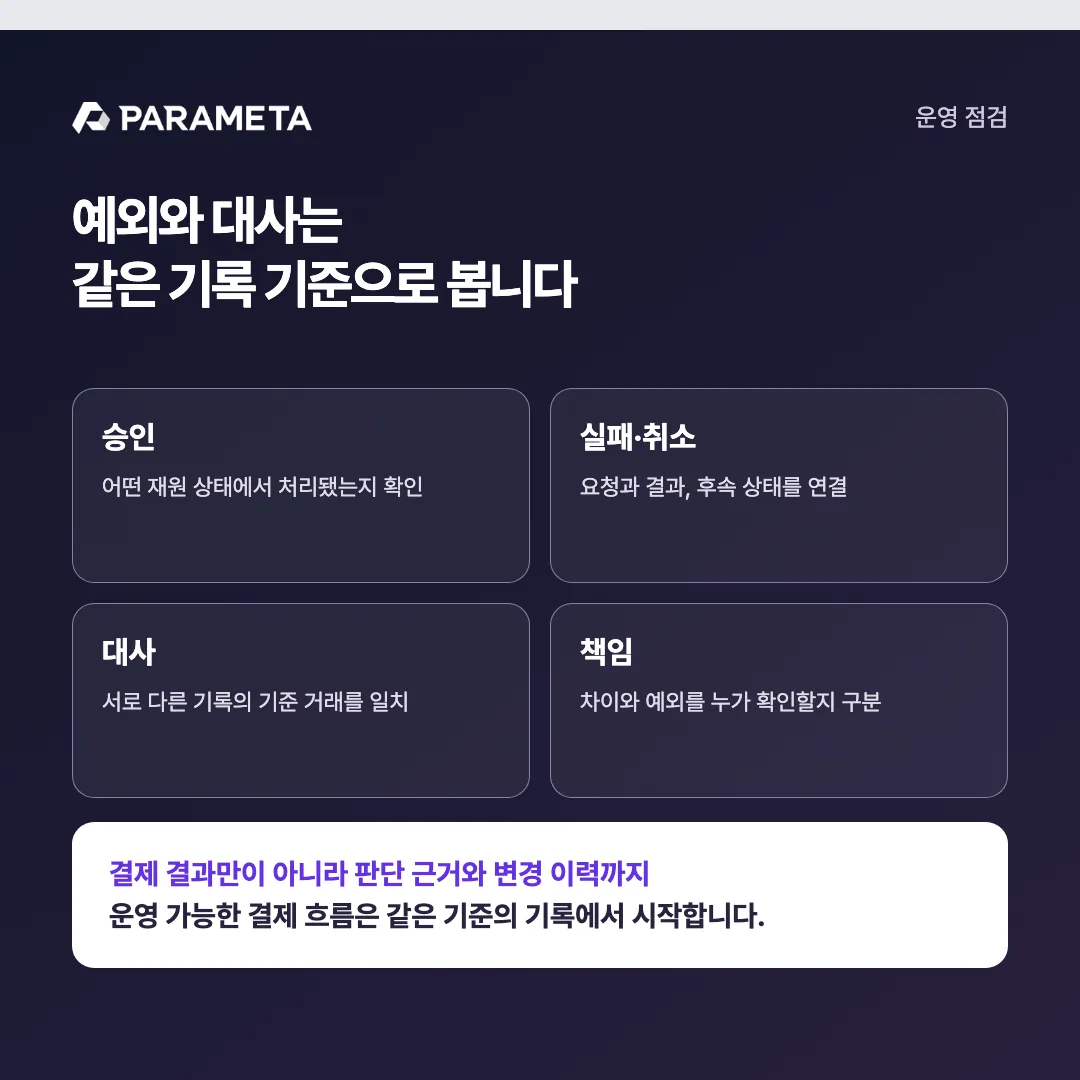
In payment operations, tracking only approved transactions isn't enough. Even when something exceptional happens — a declined request, a timeout, a cancellation, a refund — the request, its outcome, who's responsible for handling it, and its downstream status all need to stay connected.
To keep the same transaction from showing up as different states across systems, you also need to decide in advance what counts as a state change and how you confirm processing is complete. This isn't about any particular payment network's rules — it's a general standard for turning a payment flow into a record you can actually operate on.
3. Settle on Reconciliation Criteria Before Settlement
Card usage records, fund movement records, and settlement records can all update on different cycles. That's why it matters to decide in advance which entries count as the same transaction, who checks a discrepancy in amount or timing, and where the result of any adjustment gets recorded.
Reconciliation isn't just a final step for making numbers match. It can serve as the operational check that confirms the record stayed consistent all the way from payment instruction to settlement.
Where PARAMETA Is Looking
Payment methods keep changing, but operational trust is built when payment instructions, funding checks, state changes, and settlement reconciliation all connect to one another. PARAMETA continues to examine the operating conditions for this kind of trust infrastructure in the digital finance environment.
We'll keep taking a close look at what verification criteria and record structures new payment flows actually demand in operation.